
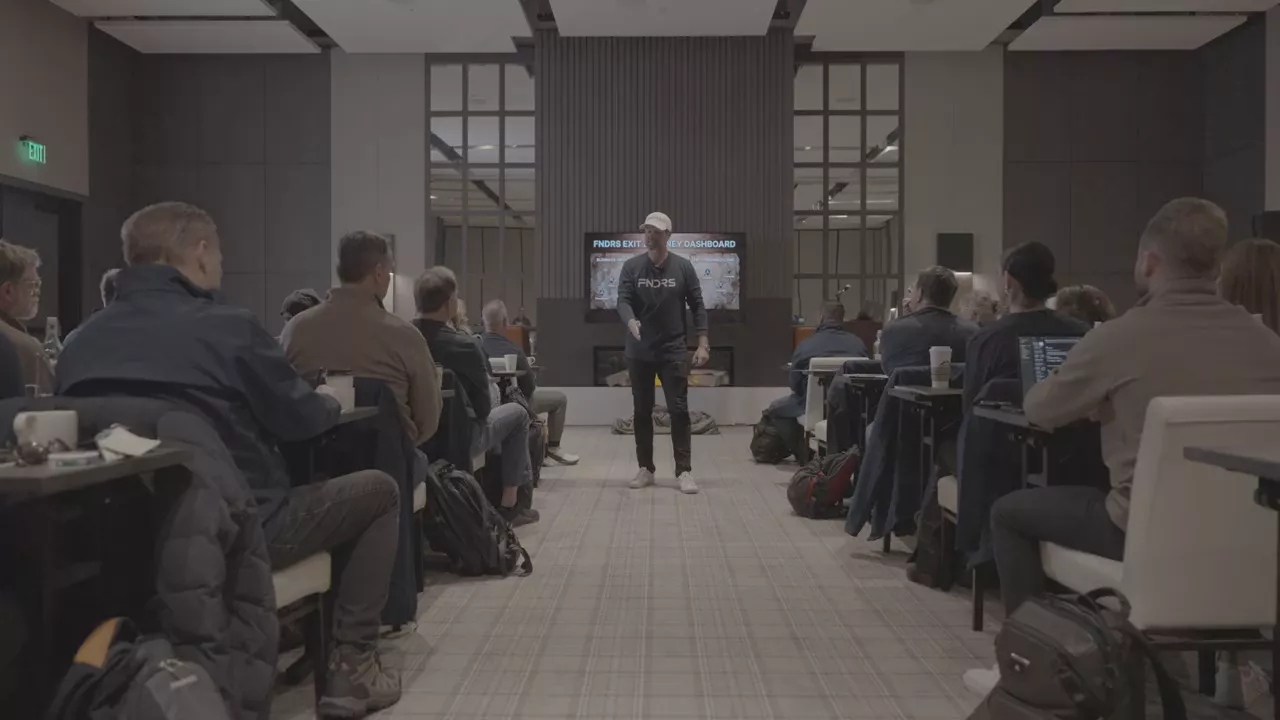
The deal team
The people who run your sale
The FNDRS deal team
You are not buying a logo. You are hiring the people who will prepare the business, take it to market, defend the numbers in diligence, and sit with you at close.
Who leads your sale
The person who answers the phone
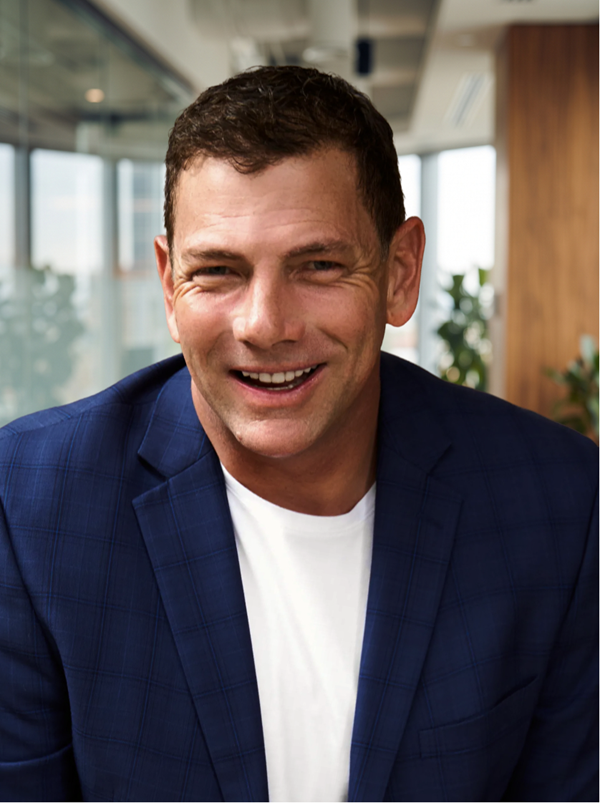
Scott Stepanik leads every FNDRS sale: the preparation, the confidential process, the negotiation, and the close. Scott runs M&A at FNDRS and has advised founder-led and middle-market businesses across the United States, Europe, Latin America, and the Middle East. The deal team works beside Scott, and the FNDRS founders stand behind it.
Leads your sale
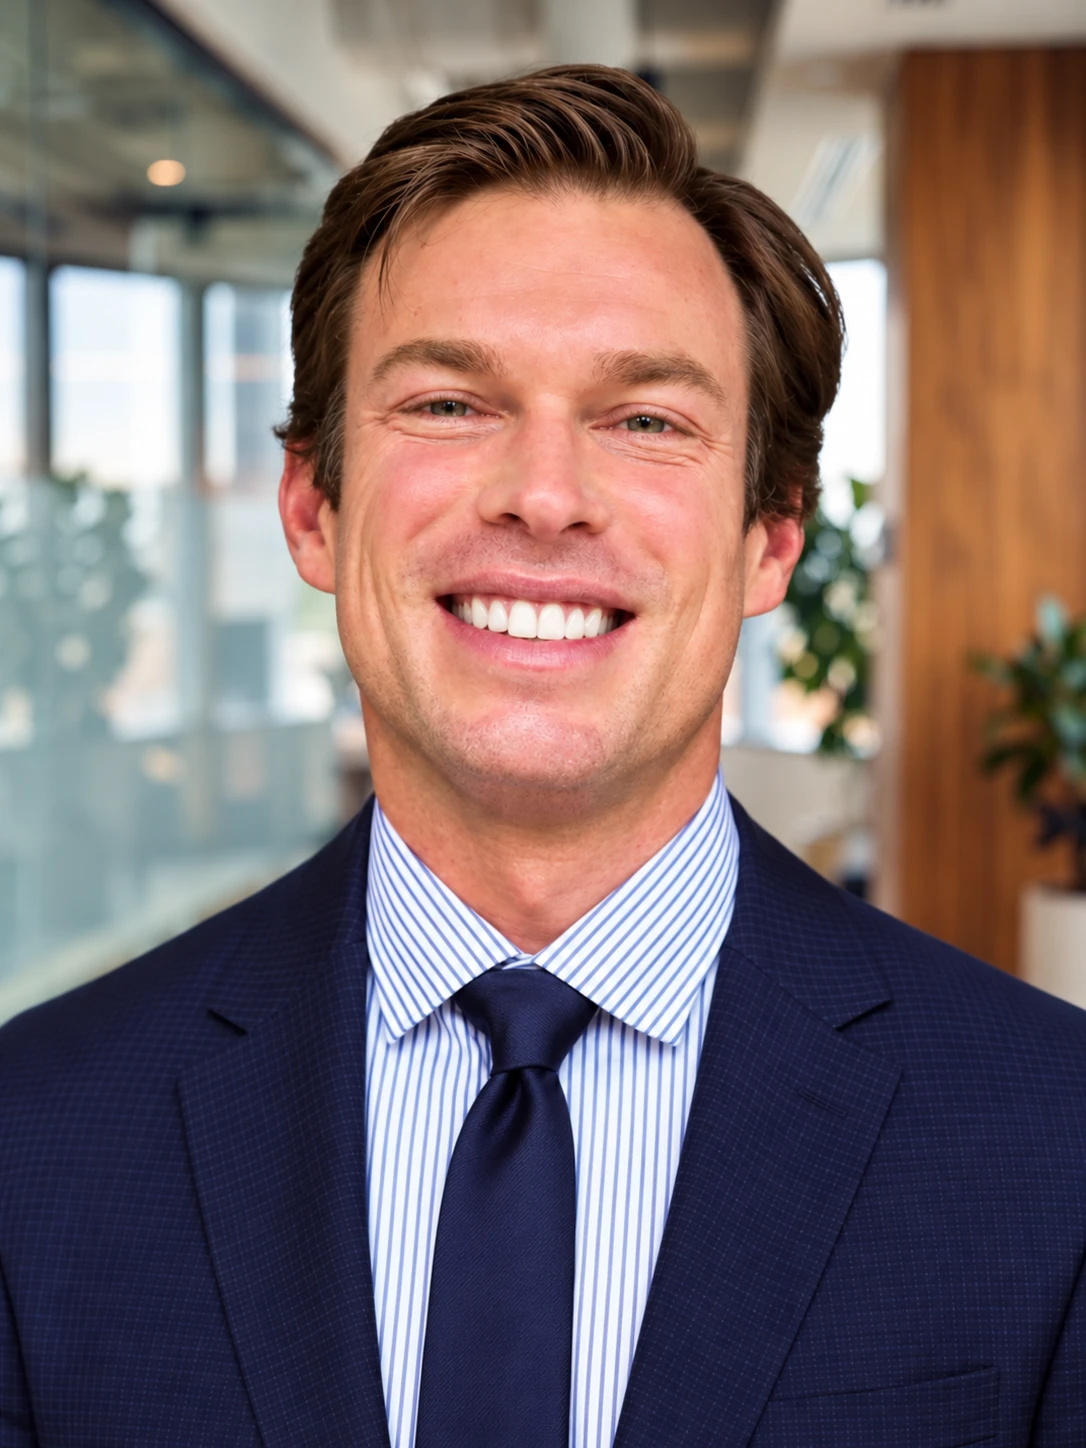
Scott Stepanik
Director of M&A
Leads every FNDRS sale: the preparation, the confidential process, the negotiation, and the close.
- Leads every FNDRS sale, from the first read of the numbers to the close
- Gives the analysis a reality check on what buyers pay for
- Prepares the CIM, the financial model, and the data room with the deal team
- Runs the confidential market process and the negotiation
The deal team
Behind the team
The FNDRS founders have built companies of their own, and they stand behind the deal team on every sale.
Phase by phase
Who does what, and who holds the clock
The Go-To-Market Analysis, then four phases, two gates, and in each phase a clock: some of it yours, some of it ours, some of it the buyer's. Nothing goes to market before you sign, and no buyer sees the CIM before you approve it.
Before anyone commits, our Director of M&A reads the business the way a buyer will.
- A discovery meeting of an hour or so, asked from a buyer's side of the table: the yellow and red flags, and where the business sits in its industry's range
- Three years of income statements and balance sheets, and the trailing twelve months, from you
- The deal workbook, and a line-by-line session with your CPA to find every add-back that can be defended
- A second meeting: three paths side by side, all cash, rolled equity, or keep growing, with the total proceeds of each after five years
- You
- How quickly the financials come in, and when your CPA is free
- The deal team
- The workbook, the session with your CPA, and the three paths
The engagement is signed. Nothing goes to market before it.
The financials rebuilt to an institutional standard, and the materials a buyer will read.
- Onboarding: the plan, the documents, and who does what
- The financials rebuilt to the standard an institutional buyer expects
- The confidential information memorandum (CIM) and the anonymous teaser written
- You review the CIM, and it is designed for buyers once you approve it
- You
- Documents, answers, and your review of the CIM
- The deal team
- The financials, the CIM, the teaser, and the buyer list
You approve the CIM. No buyer sees it before you do.
The business goes to buyers under NDA, and the offers arrive by one date.
- The business goes to a list of buyers you have seen first
- Buyers who sign an NDA receive the CIM
- Indications of interest and letters of intent arrive by a set date
- Every offer compared side by side, and reviewed with you
- A shortlist of the strongest buyers
- You
- Your say on the list and on the shortlist
- The deal team
- The outreach, the deadline, and the comparison
- The buyer
- Its own review, and its offer
The shortlist meets you, sharpens its offer, and one letter of intent is signed.
- Management meetings with the buyers on the shortlist
- Counter-offers, negotiated on price and on structure
- The winning letter of intent, signed by both sides
- You
- The meetings, and the choice of buyer
- The deal team
- Preparing you, and negotiating the terms
- The buyer
- Its final offer
The buyer checks everything, the lawyers write it down, and the money moves.
- Diligence begins, sometimes with visits on site
- The buyer's quality of earnings review, usually started early in diligence
- Definitive agreements drafted by the buyer and negotiated by every legal team
- Signing, and the wires on the day of closing
- You
- Answering diligence requests, and running the business well
- The deal team
- Managing diligence, and coordinating your attorney and CPA
- The buyer
- Its quality of earnings review, its financing, its approvals, and its lawyers' drafts
What stretches the calendar
- Financials that need restating before a buyer can rely on them
- Several legal entities, or costs shared between them
- Something the buyer's quality of earnings review turns up
- Customer, supplier, or landlord consents to the sale
- Licenses or permits that have to move to the new owner
- The buyer's financing
- A regulator, or a second country
- A key person leaving during the process
- Holidays, and the buyer's quarter-ends
Every time given here is an estimate drawn from past engagements, not a commitment. Each sale runs on its own calendar, set by how ready and how complex the company is, by the buyers and their lenders, and by the lawyers on both sides. We set a calendar with you at kickoff and revisit it as the process moves.
The record
Deals the team has advised on
FNDRS is a young firm. The people who run its sales are not new to the work: members of its M&A team have advised on sales across the United States, Europe, Latin America, and the Middle East, much of that work at prior firms. Every deal is credited to the members of the M&A team who advised on it, and no company, buyer, or advisory firm is named.
Advised by members of the FNDRS M&A team, including at prior firms
Medical device manufacturing
A precision medtech manufacturer in New York
Founder-owned and FDA-registered, with about $11.5 million of EBITDA
100%cash at close: a full founder exit, with no earn-out and no financing condition
Advised by members of the FNDRS M&A team, including at prior firms
Read the dealConsumer products
A premium personal-care brand in California
Founder-built and omnichannel, with about $8 million of EBITDA
20%equity rolled into the acquiring platform, with cash at close for the balance
Advised by members of the FNDRS M&A team, including at prior firms
Read the dealRoofing
A roofing company in Texas
A technology-enabled operator with about $6 million of EBITDA
Sold at9.5xEBITDA
Advised by members of the FNDRS M&A team, including at prior firms
Read the dealFarm equipment distribution
An equipment distributor in Minnesota
Four locations, an authorized OEM dealer, about $26 million of EBITDA
30%equity rolled by the two continuing shareholders; the other two exited in full at close
Advised by members of the FNDRS M&A team, including at prior firms
Read the dealWater infrastructure technology
A water technology company, sold across borders
A founder-led European company, sold to a platform in the Gulf
$700Mapproximate transaction value, coordinated across three jurisdictions
Advised by members of the FNDRS M&A team, including at prior firms
Read the dealSpecialty food ingredients
A family food-ingredients company, sold across borders
Family-owned in Latin America, with about $18 million of EBITDA
100%family exit at close, after the ownership was prepared for sale
Advised by members of the FNDRS M&A team, including at prior firms
Read the dealRoofing
A roofing company in Missouri
80 percent residential, 20 percent commercial
Sold at7.2xEBITDA
Advised by members of the FNDRS M&A team, including at prior firms
Read the dealRoofing
A roofing company in Minnesota
About $4.0M in EBITDA, after storm years of $5.5M to $6.5M
Sold at6.5xEBITDA
Advised by members of the FNDRS M&A team, including at prior firms
Read the deal
The four levers behind every one
- Answer every question firstWeeks of quantitative and qualitative analysis before anything goes to market, so the materials answer every question a buyer or investor will ask. Leverage at the letter of intent starts here: a factual, compelling story that leaves a buyer no risk to price.
- Tell the right storyOperational maturity, technology that sets the business apart, and the quality of its revenue, put in the terms a buyer underwrites.
- Run a competitive processA disciplined process with several qualified buyers at the table at once, so the tension between them sets the price.
- Structure to close the gapWhere buyer and seller see different numbers, the structure bridges them, so the total value to the shareholders is the number that counts, not the headline.
From the other side
A founder on working with them
George LopezLogistics and trucking · California
Questions
What founders ask about the team
Scott Stepanik. Scott leads every FNDRS sale, from the first read of the numbers to the close, backed by the deal team.
The deal team, led by Scott. It prepares the CIM, the financial model, and the data room, with business and operations support from Cecilia Camacho during preparation. You review the CIM, and no buyer sees it before you approve it.
The people who prepared the business attend with you. The exact attendance for your sale is agreed before the first meeting.
The deal team works as one, and the people who prepared your materials already know your file. How cover works for a specific engagement is set out in your engagement letter.
Nothing that identifies the company reaches a buyer before an NDA is signed. Every buyer that signs agrees not to contact your people, not to hire them, and not to go around us, and you can enforce that agreement yourself. We control who is contacted, in what order, and what each party receives.
We bring an institutional discipline to every sale: a rigorous process that puts several buyers in competition at once, and a CIM and offering materials written to the standard those buyers expect. We take each company to the right buyers through our own buyer network and database and our team's relationships, not a subscription database alone, and the team includes a CFA charterholder, which matters most in due diligence and the buyer's Quality of Earnings review.
No. On a sale we run for you, you are the client and the only one who pays us. A buyer pays us nothing, and nothing a buyer offers us changes the advice we give you.
Scott. We coordinate with your attorney, CPA, and tax advisors so the deal you signed is the deal that closes.
Meet the team before you commit
One call with Scott, who would lead your sale. No pitch deck, and no obligation after it.